Stablecoins Are Rewriting the Rules of Payments — And Markets Already Know It
The debate is over. Stablecoins are no longer a fringe experiment in crypto — and it is not just technologists or regulators saying so. Financial markets have already priced it in.
The debate is over.
Stablecoins are no longer a fringe experiment in crypto — they are rapidly emerging as core infrastructure for global payments.
What's most interesting? It's not just technologists or regulators saying this. Financial markets have already priced it in.
A $300 Billion Signal the Industry Can't Ignore
A recent IMF working paper reveals something profound:
- Stablecoin-friendly regulation triggered a ~18% decline in payment companies' valuation
- Equivalent to ~$300 billion wiped out from incumbents
This is not volatility. This is a structural repricing of the future of payments.
Markets are effectively saying:
Stablecoins will fundamentally reshape how money moves.
The Real Disruption: Not Retail — But Cross-Border
Let's be clear. Stablecoins are not just competing with cards or wallets. They are attacking the most inefficient layer of finance: cross-border payments.
Why?
- Traditional rails: slow (T+1 to T+3), expensive (multiple intermediaries)
- Stablecoins: instant settlement, near-zero cost, 24/7 programmable liquidity
This is why research consistently shows maximum disruption in cross-border players. And frankly — it makes sense.
When friction disappears, margins collapse.
A New Competitive Reality for Banks & Payment Firms
Stablecoins introduce a new model.
Open, Borderless Infrastructure
- No correspondent banking chains
- No proprietary network dependency
- Global access from day one
Programmable Money
- Smart contracts enable automation
- Real-time settlement plus embedded logic
Lower Cost of Movement
- Settlement at pennies (or less)
- Eliminates reconciliation layers
As the IMF notes, stablecoins can increase competition and reduce rents in payments.
The Strategic Divide: Who Wins vs Who Loses
Markets are already differentiating.
Most Exposed
- Cross-border payment providers
- FX-heavy intermediaries
- Legacy correspondent banking models
More Resilient
- Network-driven players (strong ecosystems)
- Firms with deep merchant/customer lock-in
Future Winners
- Players already integrating crypto/stablecoins
- Hybrid infrastructure providers (fiat plus digital rails)
The message is clear:
This is not about disruption vs survival. It's about adaptation vs irrelevance.
Regulation Is the Real Catalyst
The turning point isn't technology — it's regulation.
Stablecoins are scaling because:
- Legal clarity is emerging globally
- Reserve backing builds trust
- Institutional participation is increasing
As seen globally, regulation is becoming the unlock for enterprise-grade adoption.
Bigger Than Payments: A Monetary Shift
This goes beyond payments. Stablecoins are evolving into:
- Digital cash layers for the internet
- A new distribution channel for currencies (especially USD)
- A bridge between traditional finance and blockchain ecosystems
Some estimates suggest trillions in transaction volumes annually.
But Not Without Risks
Of course, challenges remain:
- Financial stability concerns
- Potential bank deposit disintermediation
- Regulatory fragmentation across jurisdictions
Global regulators — from IMF to ECB — are actively assessing these risks. But importantly: markets believe the benefits will outweigh the risks.
What This Means for the Future of Payments
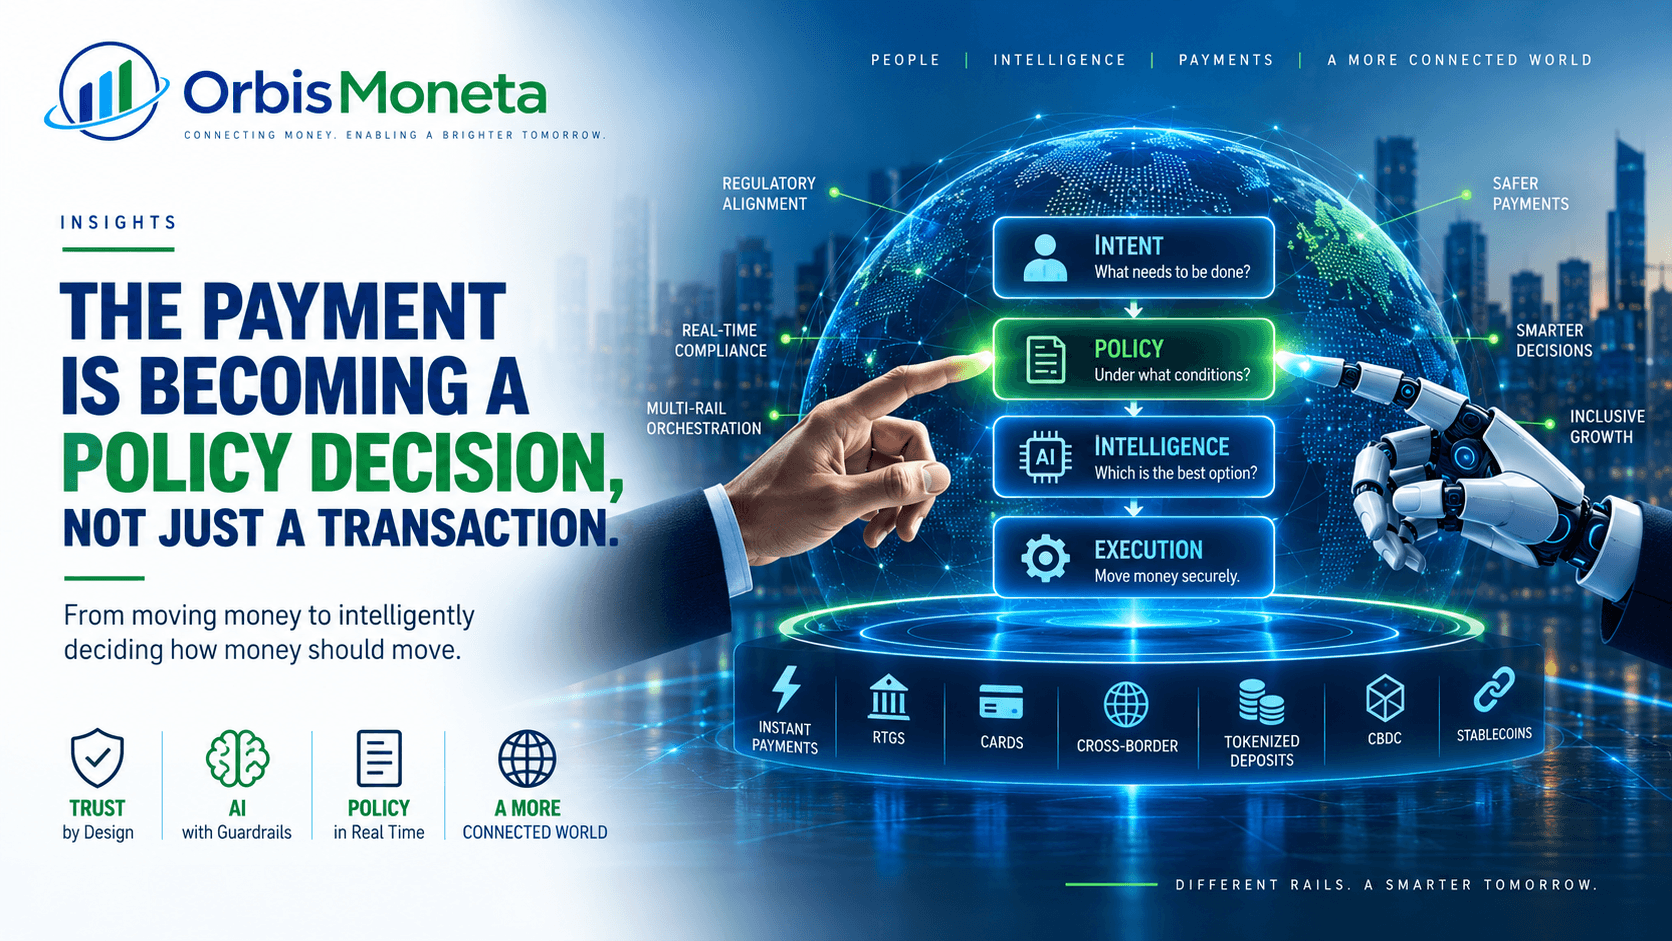
We are entering a multi-rail world:
- Traditional rails (RTGS, cards, ACH)
- CBDCs (public digital money)
- Stablecoins (private programmable money)
The winners will be those who can orchestrate across all three.
Conclusion
Stablecoins are not just another payment innovation. They represent:
A shift from institution-led payments to protocol-led value transfer.
And for the first time, markets, regulators, and institutions are aligning around this reality.
Key takeaway: stablecoins are not competing with payments — they are redefining the infrastructure of money itself.